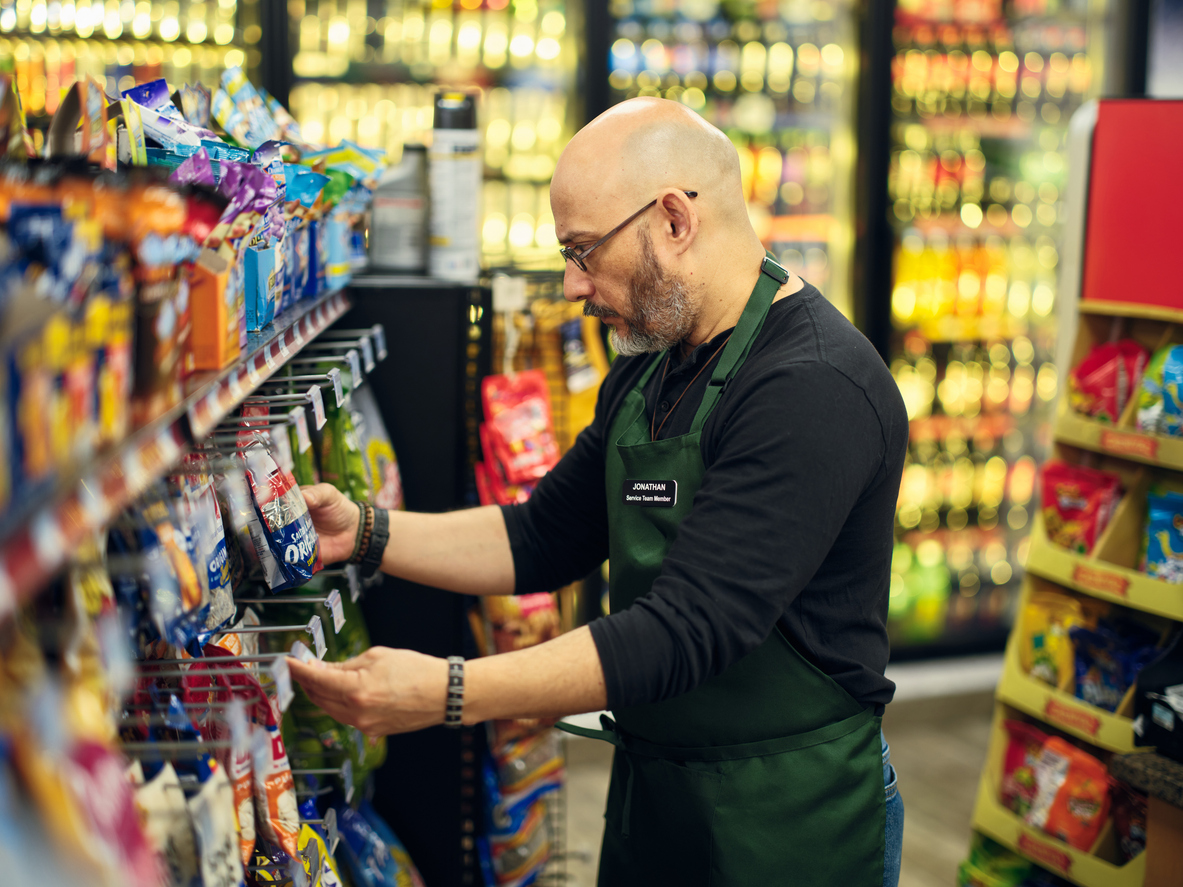
A standard-market decline doesn’t necessarily mean losing a convenience store account. For hard-to-place convenience store insurance, excess and surplus (E&S) insurance markets offer placement opportunities beyond traditional carrier appetite.
Challenging locations, extended operating hours, and complex operations may require a more specialized approach. For retail brokers with access to those markets, these accounts represent an opportunity to secure business that competitors may be unable to place.
A Large Market With Room for Specialized Expertise
The National Association of Convenience Stores (NACS) reports nearly 152,000 convenience stores across the United States, with approximately 63% of locations belonging to operators with 10 or fewer stores.
Standard carriers continue to write a substantial share of this business, including new operations. But when a particular location or exposure falls outside their guidelines, excess and surplus lines insurance gives you another way to compete for the account
What Makes a Convenience Store Difficult To Place?
Two convenience stores can look nearly identical to customers but present very different risks to an insurer. Small differences in operations, location, and services can change which carriers are willing to consider the account.
Watch for exposures such as:
- Operating hours: Stores open 24/7 may face greater scrutiny, particularly when combined with other exposures.
- Location: Elevated crime scores, theft concerns, and surrounding conditions can affect carrier appetite.
- Fuel operations: Annual gasoline volume and related exposures factor into underwriting and rating.
- Alcohol and propane sales: Refilling propane cylinders presents different considerations than exchanging prefilled tanks.
- Food preparation: Grills, fryers, and other cooking equipment may trigger protective safeguard requirements.
- Additional services: Auto repair and car wash operations introduce exposures beyond traditional convenience retailing.
While retail theft and violence remain underwriting concerns, a location’s crime score tells only part of the story. Actual loss history, security measures, and surrounding conditions can provide a more complete picture of the risk.
One Difficult Location Doesn’t Have To Derail the Account
Consider a convenience store operator with 10 locations. The standard carrier is comfortable with nine but declines the 10th because of its operating hours, crime score, or additional services. Rather than moving the entire portfolio to another market, you may be able to place that location separately through an E&S carrier while preserving standard-market coverage for the remaining stores.
The same approach applies when your client acquires another store, expands into a new territory, or adds operations outside the existing carrier’s appetite. You can pursue coverage for that individual location without disrupting the rest of the account.
Look Beyond the Initial Decline
A standard-market decline doesn’t mean you’ve exhausted your options. Identify what’s holding up the placement. Is it the 24-hour operation? The crime score? Propane refilling? Once you’ve identified the sticking point, you can approach markets with an appetite for those specific exposures.
And don’t overlook excess coverage. You may have a carrier willing to write the underlying property or general liability policy but unwilling to provide the limits your client needs. E&S markets offer another avenue for securing those limits without replacing coverage you’ve already placed.
Give Underwriters the Full Picture
For hard-to-place insurance risks, a detailed submission helps underwriters evaluate the exposures that matter. Include:
- Annual retail sales and gallons of gasoline sold
- Whether the store operates 24/7 and what happens during overnight hours
- Alcohol sales, auto repair, car washes, and propane refilling versus tank exchange
- Grills, fryers, cooking operations, and protective safeguards
- Prior claims, theft concerns, security measures, and vehicle barrier stops
For multi-location accounts, identify what sets the difficult location apart from the stores that the standard carrier has agreed to insure. Give underwriters the information they need to evaluate that location on its own merits.
Turn Difficult Placements Into New Business
When another broker walks away from a difficult convenience store account, you have an opportunity to win business they leave behind. Whether it’s a single location or one challenging store within a larger portfolio, access to E&S markets can help you pursue commercial property and casualty insurance accounts that might otherwise be lost.
Have a C-store location that no longer fits the standard market? Contact Cochrane & Company’s Property & Casualty team to discuss the risk, including individual hard-to-place locations within multi-store accounts and potential excess needs.
About Cochrane & Company
For more than six decades, Cochrane & Company has been proudly at the forefront of the insurance industry. Our experience has enabled us to innovate in powerful ways, reimagining the E&S market, and providing technology solutions that make it easy to do business with us. Licensed in all 50 states, we proudly serve clients across the nation, providing personalized and powerful solutions to help you become an even better partner for your clients. Speak to one of our experienced professionals today by calling (855) 967-0069.